


This page is also available in:
 Deutsch
At Investing Hero, I aim to provide the best investing platform reviews. To support this, some of the providers featured in reviews will generate an affiliate commission which helps pay to run this website. However, this doesn’t influence my reviews. My opinions are my own. The information provided on Investing Hero is for informational purposes only. Please read the disclaimer.
neon is still the default answer to “which Swiss account should I open”: a real Swiss bank account with no base fee, a debit Mastercard, eBill and QR payments, investing at 0.5% and a pillar 3a from 0.39%, all in one app. What has changed is that the famous free-everything has moved into plans. The free tier now carries a 0.35% card surcharge abroad, pays no interest, and gives you no free cash withdrawals at all. Every figure below is read from neon’s own price list.
Still the Swiss everyday account I recommend by default: free for everything you do in francs from a screen, held at a licensed Swiss bank (Hypothekarbank Lenzburg, not neon itself), and the rare neobank that grew into a full package with investing and pillar 3a in the same app. It is less generous than it was. The free plan now carries a 0.35% card surcharge abroad, pays no interest, and gives you no free cash withdrawals at all. If you use cash or your card abroad, budget CHF 2 a month for plus; if you do neither, free is still genuinely free.
The plans, honestly compared
neon restructured into four plans, and the fine print matters more than the marketing. neon free still covers the things you do every day at no charge: the account itself, eBill, QR bills, standing orders, LSV direct debits, Swiss payments and Spaces. What it no longer covers is cash and travel. The free plan adds 0.35% to card payments in foreign currencies and 1.5% to ATM withdrawals abroad, and it gets no free cash withdrawals in Switzerland at all. plus (CHF 2/month) removes the card surcharge, global (CHF 8) adds travel, cyber and shopping insurance, and metal (CHF 15) makes withdrawals free worldwide and wraps the card in steel.
| Plan | Per month | Card FX abroad | ATM abroad | Free CHF ATMs a month |
|---|---|---|---|---|
| neon free | CHF 0 | 0.35% | 1.5% plus the 0.35% | None. CHF 2.50 each |
| neon plus | CHF 2 | 0% | 1.0% | 2, then CHF 2.50 |
| neon global | CHF 8 | 0% | 0.5% | 3, then CHF 2.50 |
| neon metal | CHF 15 | 0% | 0% | 5, then CHF 2.50 |
What the money buys as you go up: plus adds phone support, global adds travel, cyber and shopping insurance plus 20% back on Wise transfer fees, and metal adds a steel card, phone insurance and 40% back on Wise. The first card costs CHF 20 on free and plus, and is free on global and metal. One thing the marketing page does not put in front of you: global and metal tie you in for 12 months. free and plus you can drop whenever you like.
Source: neon’s plans and prices page and the official services and prices PDF (status 6 November 2025), both checked 21 September 2026. Annual billing takes 17% off the paid tiers. neon green costs CHF 3 a month plus a one-off CHF 20 for the wooden card; neon duo is CHF 3 per person, so CHF 6 a month for a couple.
Two questions settle the choice: how often you take cash out in Switzerland, and how often you pay by card abroad.
Which plan, in one sentence each: free if you rarely need cash and rarely pay abroad; plus if you withdraw cash in Switzerland more than about twice a month, or spend heavily by card abroad; global if you would otherwise buy travel insurance anyway; metal only if free worldwide withdrawals and a steel card are worth CHF 150 a year to you.
Where the CHF 2 a month pays for itself. On the card surcharge alone, plus costs CHF 24 a year and saves you 0.35%, so it breaks even at about CHF 6,900 of foreign-currency card spending a year. Two normal holidays do not get most people there, whatever the marketing suggests.
Cash decides it. On neon free every Swiss ATM withdrawal costs CHF 2.50. Take money out twice a month and that is CHF 60 a year, against CHF 24 for plus, which gives you two free withdrawals a month. On those numbers plus pays for itself at roughly one withdrawal a month, and everything you save on card payments abroad is on top.
Or pay neon nothing and use the tills. Cashback at Coop, ALDI and LIDL checkouts is free on every plan including free, with a minimum purchase of CHF 10. If your cash comes out of a supermarket till rather than an ATM, the free plan stays free and there is no reason to upgrade.
The neon card: debit, not credit
A lot of people arrive here searching for the “neon credit card”. There isn’t one. neon issues a debit Mastercard, issued by Hypothekarbank Lenzburg, and every payment comes straight out of your account balance. There is no credit line, no monthly bill and no interest-bearing revolving balance.
For most people that is the right product and not a compromise. It matters in three places, though: some hotel and car-hire deposits still prefer a true credit card, a debit card earns you no purchase protection or cashback of the kind a rewards card gives, and there is no float between spending the money and paying for it. If you want cashback on top of a free Swiss account, the usual pairing is a neon account for the banking and a separate free cashback card, which is what my credit card comparison is for.
What the card costs, none of which appears in the plan table:
| Card charge | free | plus | global | metal |
|---|---|---|---|---|
| First card | CHF 20 | CHF 20 | Free | Free |
| Replacement when it expires | CHF 10 | CHF 10 | Free | Free |
| Replacement if lost or damaged | CHF 20 | CHF 20 | CHF 20 | CHF 20 to 80 |
| Shipping a replacement abroad | CHF 80 | CHF 80 | Free | Free |
| Second card on the same account | Not currently possible on any plan | |||
plus does not include a free card. Only global and metal do. And the card expires, so the CHF 10 renewal on free and plus comes round again every few years. A second card for a partner is not available at all: that is what neon duo is for.
TWINT works, but not the way it does at a normal bank. There is no bank-linked TWINT; you have to use the TWINT Prepaid app, register your neon card, enter your IBAN and wait one to two working days for the bank authorisation. Top-ups up to CHF 200 are available straight away. It works, and it is clumsier than the TWINT you get with PostFinance or a cantonal bank.
What neon pays on your balance: nothing
The short answer to “neon Zinsen” is 0% on all four plans, on the main account and on Spaces alike, and it has been since 1 December 2024, when neon removed the last of it after the Swiss National Bank’s rate cuts.
That is the Swiss market rather than a neon failing, and plenty of traditional accounts pay a rounding error too. It does settle what the account is for. neon is where your money passes through. A current account paying nothing is fine for a month of spending and a buffer. Anything with a longer horizon belongs in a pillar 3a or invested, rather than in a Space earning zero while inflation works on it. Spaces are a good budgeting tool and a poor savings account.
neon used to pay interest, and not a trivial amount: 0.90% in 2023 and into early 2024, stepping down through 0.75%, 0.50% and 0.10% before reaching zero in December 2024. Readers who opened an account in 2023 did not imagine it. That withdrawal, more than any single fee, is what the unhappy reviews are about.
How neon’s everyday account compares with other everyday accounts, from source-verified data. Pick another account to switch the comparison.
neon comparison
| neon | Yuh | |
|---|---|---|
| Account fee | 0 CHF (free plan) | Free |
| Card | First card CHF 20; replacement CHF 20 | Free (physical + virtual); replacement fee not published |
| Card payments abroad | 0.35% card surcharge; ATM abroad 1.5% | 0.95% flat |
| TWINT | TWINT Prepaid only | Yes |
| Apple Pay | Yes | Yes |
| Interest | 0% (none since Dec 2024) | 0% (saving projects) |
| Notes | Plans changed on 18 Sep 2026: the free plan now charges for the first card and a 0.35% FX surcharge. TWINT only via TWINT Prepaid. | No interest on balances. FX is a flat 0.95% with no weekend surcharge. |
| Reader deal | CHF 10 welcome bonus with code investinghero | CHF 50 trading credit + 250 Swissqoins with code YUHINVESTINGHERO |
| My rating | ★ 4.5 | ★ 4.6 |
| Full review | – | Read the full Yuh review → |
Checked at source: neon 23 September 2026 · Yuh 23 September 2026
More than an account: invest and pillar 3a
neon invest trades all ETFs and Swiss shares at 0.5% and international shares at 1%, with no custody fee and no currency-exchange fee on trades, and the partner ETFs inside the investment plan trade at 0%. Two things the headline rate leaves out: outside the investment plan there is a CHF 1 minimum fee per trade, which bites on anything under about CHF 200, and Swiss stamp duty of 0.075% on Swiss securities and 0.150% on foreign ones is added on top. neon passes that through and says so, which is more than some brokers manage.
The pillar 3a put the whole retirement setup in the same app, on a fee that falls with your balance: 0.45% at the bottom, stepping down through 0.44%, 0.43% and 0.41% to 0.39% from CHF 50,000, and it drops automatically from the next quarter once you cross a threshold. That ladder is unusually granular for Switzerland, where most 3a providers charge one flat rate whatever your balance.
A falling fee is rare in Switzerland, but neon is not alone in it. Selma publishes balance tiers of its own, 0.68% falling to 0.42%. Two providers look like they belong in that company and do not: frankly’s discount tracks the platform’s total volume rather than your balance, and VIAC’s structure makes small balances cheaper.
How it compares with finpension. finpension charges a flat 0.39%, genuinely all-in, though its own fee page puts the underlying fund TER at 0.00 to 0.02%, so call it 0.39 to 0.41%. Below CHF 50,000 finpension wins. Above CHF 50,000 the two are level on three of neon’s five strategies; finpension only stays ahead on Ambitious 80 and Offensive 100, where neon’s indirect fund costs add 0.07% and 0.04%. Every gap here is two to seven basis points. Choose between these two on whether you want your 3a inside your banking app or in a dedicated one. On fees you are choosing between rounding errors.
There is now an insurance brokerage inside the app too, under a “Benefits” tab, through a partnership with Smile. Car, household, motorbike, pet and legal-protection cover, with a discount for neon users. I have not bought through it and cannot tell you whether the quotes are competitive, so treat it as a convenience rather than a recommendation, and price it against a broker before you buy.
Who holds your money, and what is protected. neon is not a bank and holds no banking licence. In its own words: “No, because neon is not a bank. The account is managed by Hypothekarbank Lenzburg, which has a banking licence.” neon is the app and the brand; Hypothekarbank Lenzburg is the licensed Swiss bank holding the account and issuing the card.
What that means in practice: your balance, including anything sitting in Spaces, carries the standard Swiss deposit insurance of up to CHF 100,000 per personal account. A neon duo joint account gets its own separate CHF 100,000 on top of that.
Deposit insurance covers bank balances only. It does not cover money you have invested through neon invest or neon 3a. Those sit as segregated assets, a different and in some ways stronger protection, because they remain legally yours in a bankruptcy rather than being capped at a franc figure. Do not add the two together in your head.
Opening an account with neon
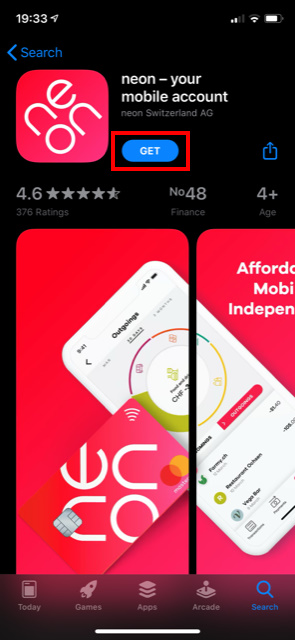
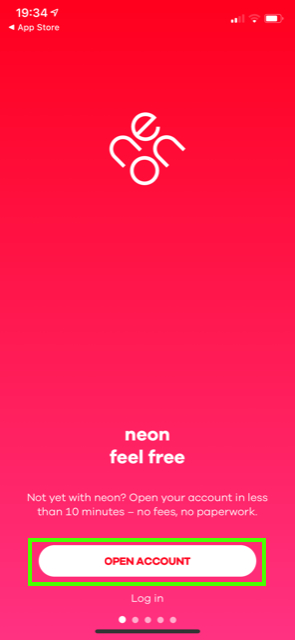
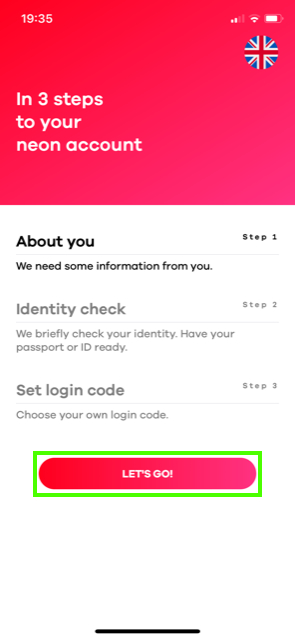
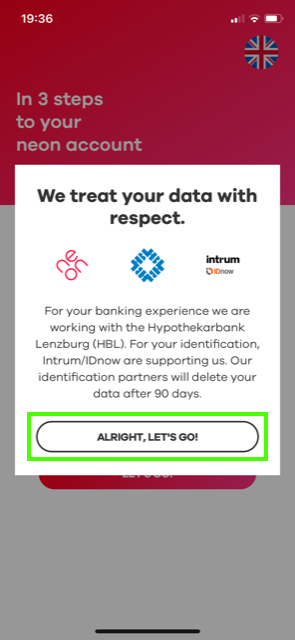
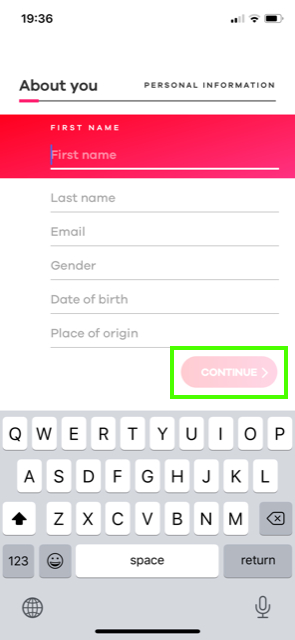
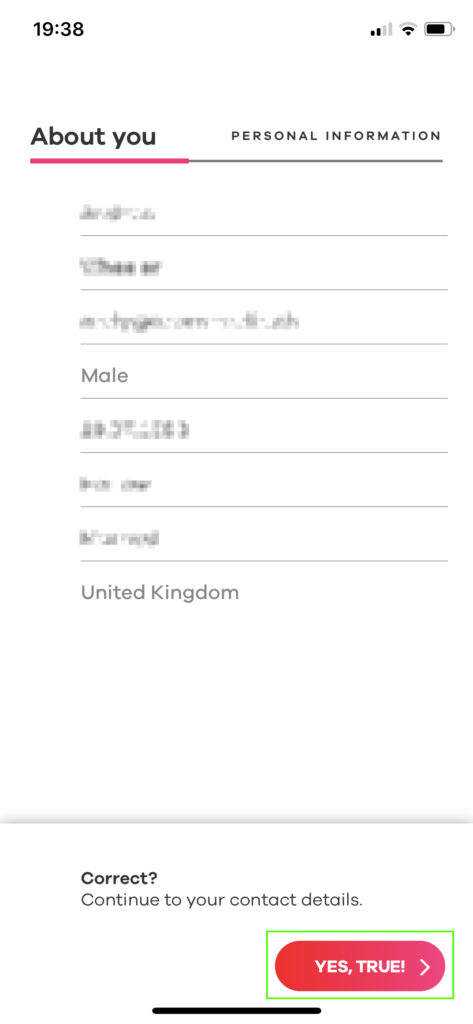
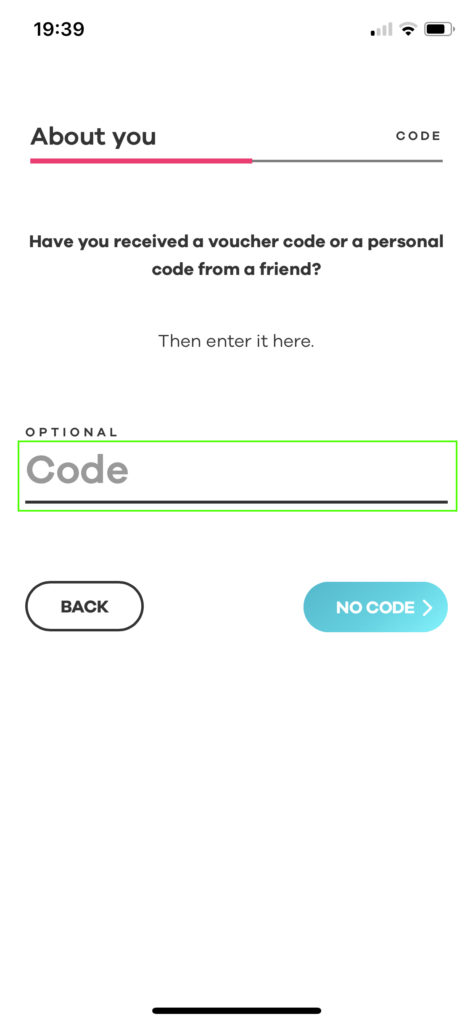
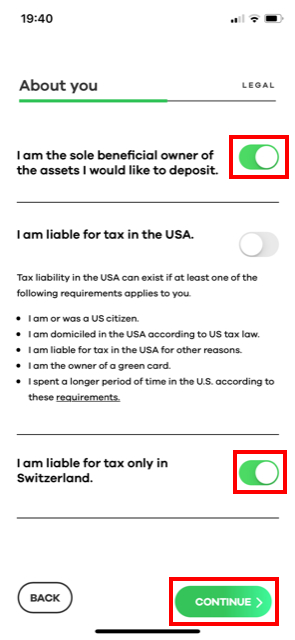
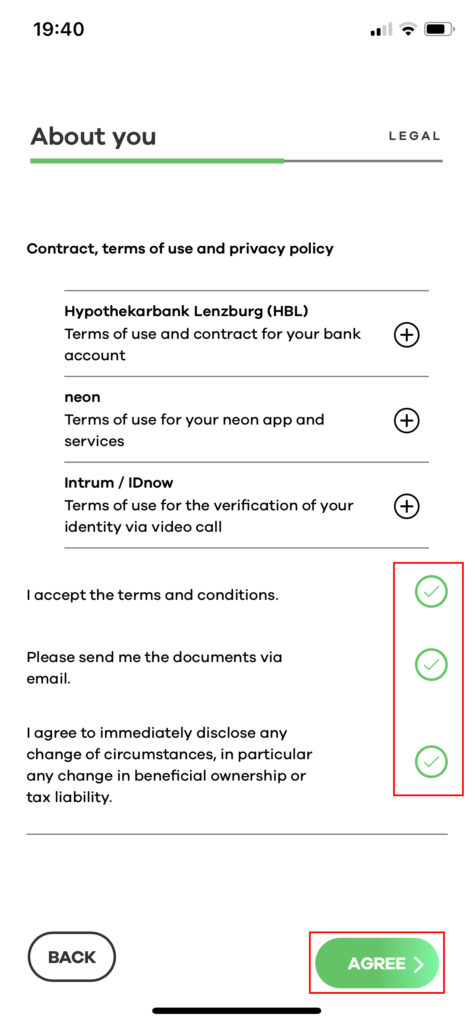
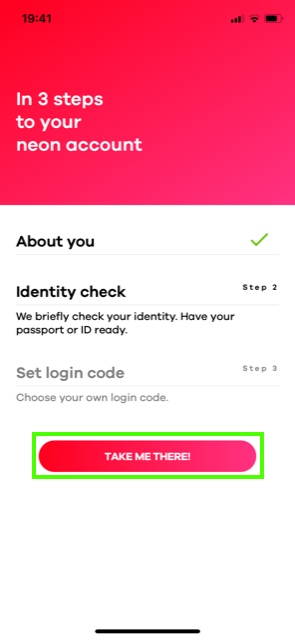
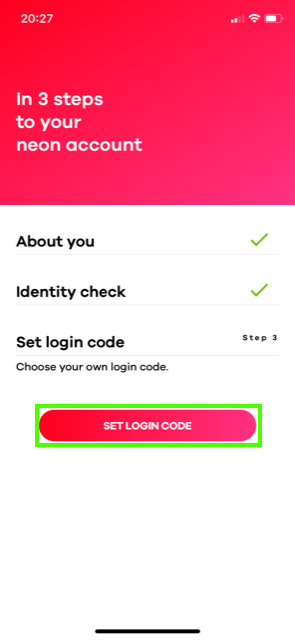
Ten minutes, phone only, with a video identity check at the end of it. The screens in the three steps below are my own opening, one by one. neon has restyled the app since, and the three-step structure and the questions it asks are unchanged, so it still tells you what you are walking into.
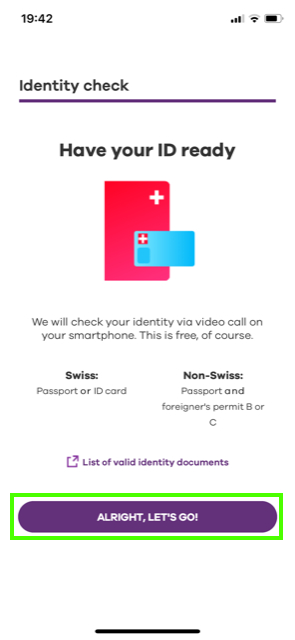
Have these ready before you start. If you are Swiss: your passport or ID card. If you are not: your passport and your permit B or C, both. Then a quiet room with decent light and a stable connection, because the identity check is a live video call, not a photo upload. Everything else is form-filling.
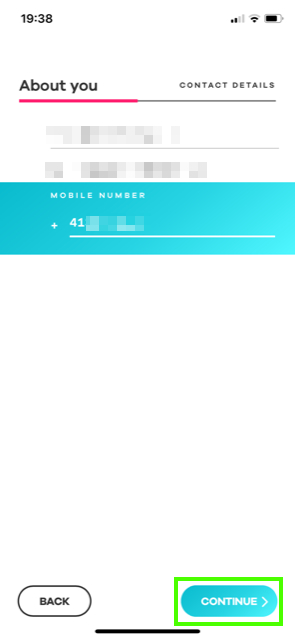
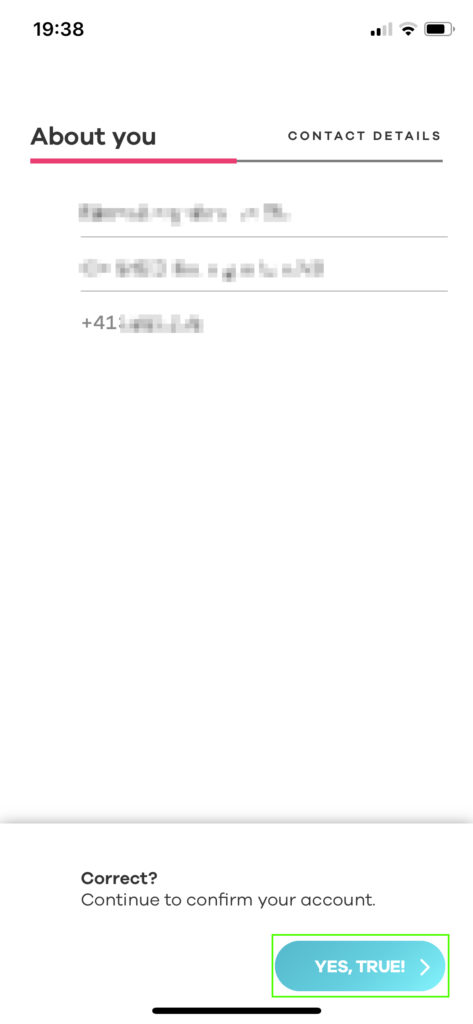
Step 1: About you
It starts on neon’s website and moves into the app almost immediately. The app numbers the three steps and shows you where you are in them, which is more than most banks manage.
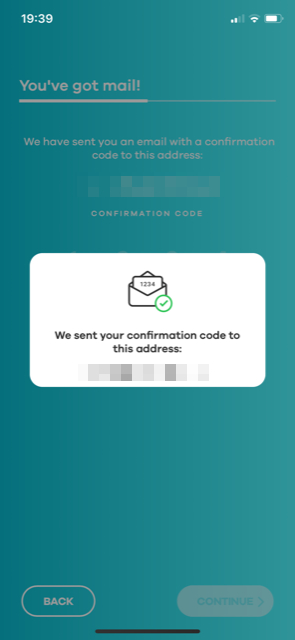
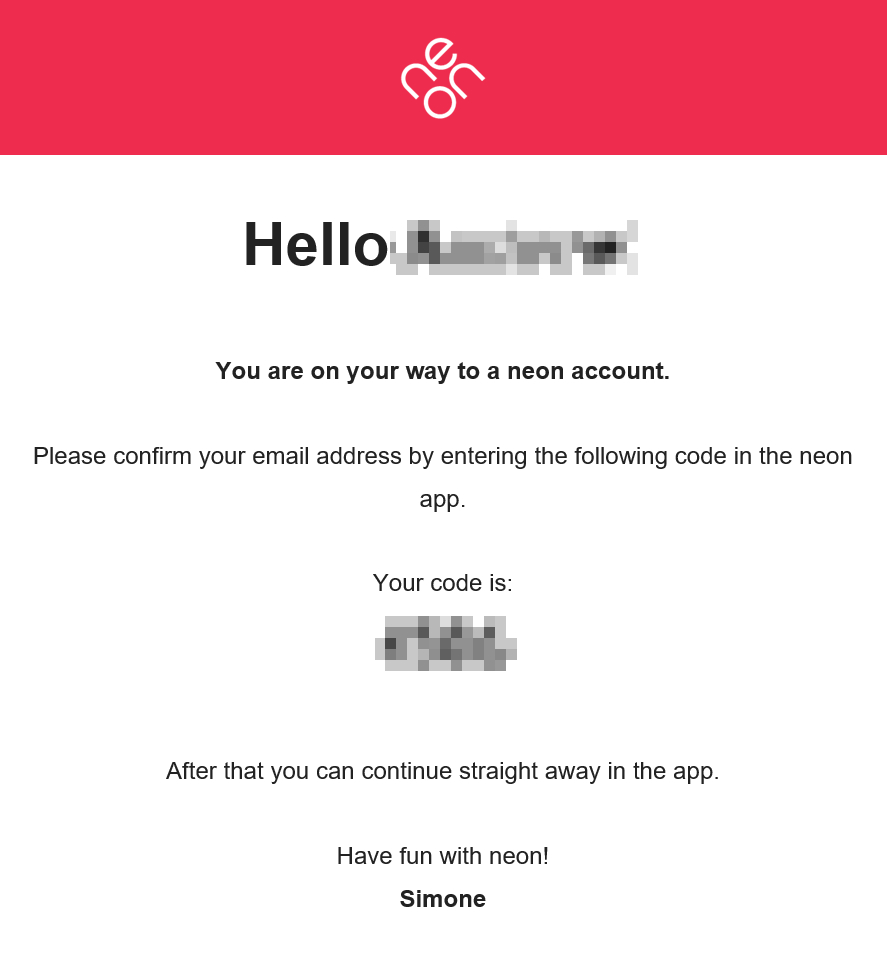
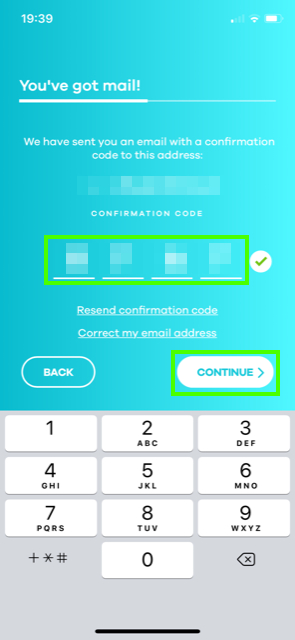
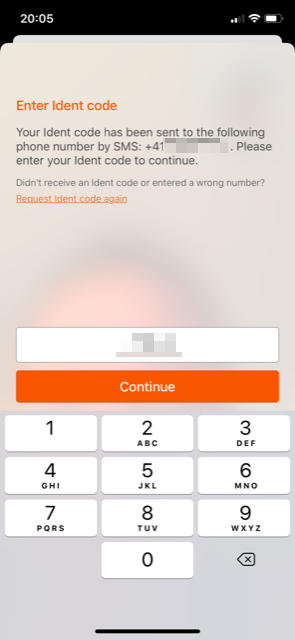
The code from that email goes straight back into the app, and the next three screens are the ones worth slowing down for.
Step 2: The identity check
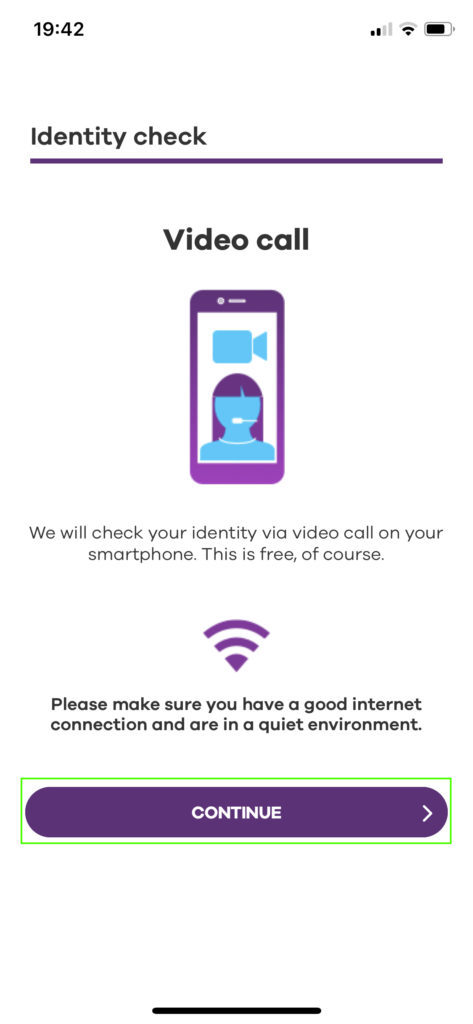
This is the only part that is not form-filling, and the only part that can go wrong. It is a live video call with an agent from IDnow, so it needs a quiet room, decent light and a connection that will not drop halfway through. Budget five minutes and do not try it on a train.
Step 3: Set your login code
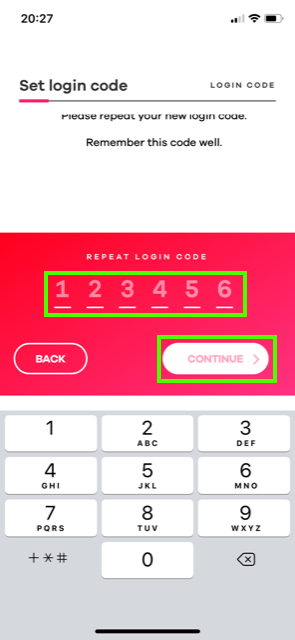
The short one. Choose a six-digit code, repeat it, and you are through.
What happens after the last tap
The slow parts are not the form. They are the video call slot and the wait for the card: the contract number arrives by email within one to two working days, and the card comes by post after that. Plan for about a week before you can pay with it. If you are switching your salary across, open the account first, wait for the card to land, and only then move the standing orders. Switching in the other order is how people end up with a direct debit bouncing on an account they cannot yet use.
What other neon users say
My own experience is one account. Here is what a few thousand other people think, checked on 21 September 2026, with the awkward numbers left in.
| Where | Score | Based on |
|---|---|---|
| Trustpilot | 3.2 / 5 | 343 reviews |
| Apple App Store (Swiss storefront) | 4.5 / 5 | 7,854 ratings |
| Google Play | 4.4 / 5 | 11,100 reviews |
3.2 out of 5 reads like mediocrity, and the distribution says something different. 40% five-star, 37% one-star, with almost nothing in the middle: 46% sit at four or five stars, 47% sit at one or two. People either love this bank or feel let down by it, and very few land in between.
The complaint is consistent enough to name, and it is almost never that something is broken. It is the erosion of the original free offer: the FX surcharge that arrived on the free plan, the charges for card replacement, the cash withdrawals that stopped being free, the interest that was withdrawn in December 2024. People who joined a fee-free bank in 2021 do not feel they are using the same product in 2026. The second theme is support, which is email-only unless you pay. There is no phone number to call when a card fails abroad on the free plan.
I checked those complaints against neon’s own price list and they hold up. The FX surcharge is real, the free plan has no free withdrawals, and the interest went to zero. The reviewers are describing a product that got less generous, and they are right about that. It is still the account I would open.
In neon’s favour: they reply to 96% of negative reviews, usually with a specific answer rather than a template. The gap between 4.4 on Google Play and 3.2 on Trustpilot is the ordinary pattern, where app stores catch the satisfied everyday user and Trustpilot catches the person with a grievance. Read both, not whichever one suits the argument.
neon pros and cons
| Pros | Cons |
|
|
My rules for the everyday account
- Pick the plan on cash, not on holidays. The card surcharge needs about CHF 6,900 of foreign spending a year before plus pays for itself. One Swiss ATM withdrawal a month does it on its own.
- Salary in, everything follows. The account only simplifies your life if it’s the main one; half-used neobank accounts just add passwords.
- Use Spaces as your budget. Rent, taxes and holidays in separate Spaces is the entire budgeting system most people need.
- Invest via the plan ETFs first. The 0% investment-plan partner funds beat the 0.5% standard rate for monthly saving.
- Take your cash out at a till, not a machine. On neon free every ATM withdrawal costs CHF 2.50. Cashback at a Coop, ALDI or LIDL checkout costs nothing on any plan, with a CHF 10 minimum purchase.
- Do not leave savings sitting in a Space. They pay 0% and have since December 2024. Spaces are for organising this month’s money, not for growing next year’s.
The test costs one card fee. Open neon free, pay the CHF 20 for the card, route a month of spending through it and see whether the app clicks for you. No base fee is ticking while you decide, nothing locks you in on the free plan, and if it becomes your main account you can move up to plus later in about two minutes.
neon FAQ
Is neon safe and legit?
Yes, with one precision that matters: neon itself is not a bank and holds no banking licence. Your account is held and managed by Hypothekarbank Lenzburg, which is a licensed Swiss bank, and your balance including Spaces carries the standard Swiss deposit protection of up to CHF 100,000. A neon duo joint account gets its own separate CHF 100,000 on top.
Is neon really free?
Free for everything you do in francs from a screen: the account, eBill, QR bills, standing orders, LSV, Swiss transfers and Spaces. Not free for three things. The card costs CHF 20 up front and CHF 10 again each time it expires, card payments in a foreign currency carry a 0.35% surcharge, and cash withdrawals cost CHF 2.50 every time, because the free plan has no free withdrawals at all. Take your cash as cashback at a Coop, ALDI or LIDL till instead and it costs nothing.
Which neon plan should I choose?
Cash decides it, not holidays. On the FX surcharge alone, plus at CHF 2 a month only pays for itself at around CHF 6,900 of foreign-currency card spending a year. But plus also gives you two free Swiss ATM withdrawals a month against none on free, so if you take cash out even once a month it already pays. Stay on free if you rarely need cash and rarely pay abroad; take global only if you would have bought travel insurance anyway; take metal only if free worldwide withdrawals are worth CHF 150 a year. Note that global and metal tie you in for 12 months, and annual billing cuts 17% off.
Can I invest with neon?
Yes: all ETFs and Swiss shares at 0.5% per trade, international shares at 1%, no custody fee, and the partner ETFs inside the investment plan at 0%. Two costs the headline rate leaves out: a CHF 1 minimum fee per trade outside the investment plan, which bites on anything under about CHF 200, and Swiss stamp duty of 0.075% or 0.150% on top. For a hands-off portfolio a robo-advisor still does more for you; for monthly ETF saving inside your banking app, the 0% partner funds are hard to beat. Full detail in my neon invest review.
What about the neon pillar 3a?
A fully integrated 3a inside the same app, on a fee that steps down with your balance from 0.45% to 0.39% above CHF 50,000, reducing automatically from the next quarter once you cross a threshold. On price it sits close to the specialists: finpension at 0.39% wins below CHF 50,000, and above it the two are level on three of neon’s five strategies. The gaps are two to seven basis points, so choose on whether you want your 3a in your banking app, not on the fee. Full detail in my neon 3a review.
How does the neon promo code for CHF 10 work?
Enter the code investinghero during sign-up and the bonus lands after your account is active. It’s neon’s standard referral mechanism, nothing to claim afterwards.
neon or Yuh or Zak?
neon for most people, because it is the fuller product: banking, investing and pillar 3a in one app, on a published price list. Yuh is the closest rival and the better pick if trading and 3a matter more to you than everyday banking does. Zak is a genuinely free Bank Cler account and suits people who want a Swiss bank behind the app without the extras. My best bank in Switzerland shortlist ranks all three side by side.
Can I deposit cash into neon?
Not directly. neon has no counters, and its price list lists cash deposits as “not possible”. There are two documented workarounds and both are slow. You can buy a TWINT top-up code with cash at a post office or at Coop and unload it to your neon IBAN through the TWINT Prepaid app, which takes two to three working days. Or you can generate a QR deposit slip and pay it in cash at a post office counter, which Swiss Post charges you for. If regular cash deposits are part of your life, keep a traditional account alongside neon.
Does neon offer a credit card?
No. neon issues a debit Mastercard, issued by Hypothekarbank Lenzburg, and payments come straight out of your balance. There is no credit line and no monthly bill. That is the right product for most people, but it matters if you need a true credit card for hotel or car-hire deposits, or if you want purchase protection or cashback, in which case pair the account with a free cashback card from my credit card comparison. A second card on the same account is not currently available on any plan.
Does neon pay interest?
No. 0% on every plan, on the main account and on Spaces alike, and that has been the case since 1 December 2024. neon did pay interest before that, up to 0.90% in 2023, which is why so many long-standing customers feel the product has been quietly downgraded. Treat neon as the account your money passes through, not the place it sits.
Compare & choose
The other comparisons on Investing Hero, each built the same way: every fee read from the provider’s own pricing page.
My best bank in Switzerland shortlist puts neon next to every other Swiss account, and covers the free-versus-licensed question.
How this review is kept current. Every neon figure on this page was re-read from neon’s own pages and its official price list on 21 September 2026, never from a comparison site. The referral code and bonus come from my standing neon partnership, which pays me a commission and does not change a word of the above.
Sources. All neon figures were read from neon’s own pages on 21 September 2026: the plans and prices page and, where the two differ, the authoritative services and prices PDF (status 6 November 2025), which is where the plan grid, the 0.35% FX surcharge, the ATM ladder, the card fees, the 0% interest line and the minimum terms come from. Individual FAQ pages on neon-free.ch cover cash deposits, TWINT, free cashback and the banking licence. Investing and pillar 3a figures are from my own neon invest and neon 3a research files. finpension figures are from finpension.ch. Selma’s 3a fee tiers are from selma.com. Ratings were read from Trustpilot, the Swiss Apple App Store and Google Play on 21 September 2026. Nothing on this page is quoted from a comparison site. Educational content, not financial advice.


