


This page is also available in:
 Deutsch
At Investing Hero, I aim to provide the best investing platform reviews. To support this, some of the providers featured in reviews will generate an affiliate commission which helps pay to run this website. However, this doesn’t influence my reviews. My opinions are my own. The information provided on Investing Hero is for informational purposes only. Please read the disclaimer.
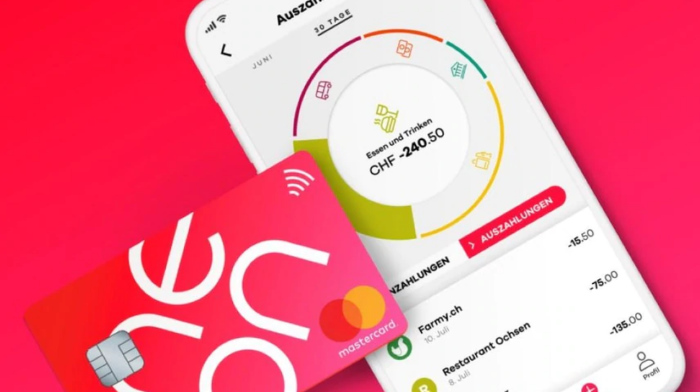
neon invest is the trading side of Switzerland’s favourite free bank account: over 500 stocks, ETFs and crypto-ETPs inside the neon app, at 0.5% per trade for ETFs and Swiss shares with no custody fee and no currency-exchange margin. The investment plan even drops selected ETFs to 0%. The costs neon’s marketing does not lead with: a 1% rate on international shares, Swiss stamp duty, and the BX Swiss spread.
The simplest way in Switzerland to start buying ETFs with money you already have in your everyday account: no custody fee, no FX margin, and a savings plan that buys selected ETFs for 0%. It is built for monthly savers, not traders. Know the three real costs before you judge the 0.5%: international shares cost 1%, every trade carries federal stamp duty, and prices come from BX Swiss, where the spread can widen when US markets are closed.
neon invest pros and cons
| Pros | Cons |
|
|
What neon invest actually costs
neon’s investing price list is short, and the same on all four account plans, from neon free to neon metal. Every figure below comes from neon’s own pricing page and invest FAQ, read on 21 September 2026.
| Item | Cost at neon invest |
|---|---|
| Custody fee | CHF 0 |
| ETFs and Swiss shares | 0.5% per trade |
| International shares | 1.0% per trade |
| Currency exchange on trades | CHF 0, no margin added |
| Selected ETFs in the investment plan | 0% purchase fee |
| Minimum fee outside the investment plan | CHF 1 per trade |
| Swiss stamp duty on each trade | 0.075% Swiss, 0.15% foreign securities |
| The account around it | neon free costs CHF 0 a month, first card CHF 20 one-time |
0.5% decoded. The percentage is not the whole price of a trade. The full bill is the trading fee, plus stamp duty, plus whatever the BX Swiss spread costs you at that moment. On a CHF 500 ETF purchase that is CHF 2.50 fee plus 38 Rappen stamp duty, about CHF 2.90 before the spread. The minimum fee matters at the small end: below CHF 200 an ad-hoc ETF trade always costs CHF 1, which on CHF 50 is an effective 2%. The investment plan waives that minimum, which is one of several reasons the plan is the better way in.
What that means for a CHF 200 monthly plan
Put CHF 200 a month into one of the 0% investment plan ETFs, for example the Vanguard FTSE all-world ETF on neon’s 0% list, and the trading fee is exactly nothing. What remains is federal stamp duty, 30 Rappen per instalment on a foreign-domiciled fund. Over a year you invest CHF 2’400 and pay CHF 3.60 in total transaction costs. There is no cheaper regular ETF savings plan at a Swiss-regulated provider that I know of, and I say that as someone who compares these fee tables for a living.
The investment plan is the actual product
The ad-hoc trading screen is fine, but the investment plan is what neon invest is genuinely good at. You pick up to six assets, set a monthly amount, and neon buys them automatically. Amounts, assets and execution dates can be changed at any time, and the CHF 1 minimum fee never applies to plan orders.
The 0% list is the part worth reading. Through partner arrangements, a set of assets marked “0% investment plan” in the app costs nothing to buy in a plan: at my check it included global equity ETFs from Vanguard and Xtrackers, Swisscanto ESG world and eurozone funds, a ZKB gold ETF, a commodities ETF, high-dividend ETFs, and the Xtrackers bitcoin and ethereum ETPs. For most people, one world ETF from that list covers the whole job.
One plan, one world ETF, done. Take one idea from this page: a monthly plan into one broad world ETF from the 0% list gives you a diversified portfolio at effectively zero fees, inside the account your salary already lands in. Everything else on this page is detail. What the plan will not do is pick the amount for you: if you want the whole portfolio managed, that is a robo-advisor job.
Where your trades happen: BX Swiss and the spread
neon executes on BX Swiss, the former Bern stock exchange, and shows all prices in Swiss francs. That setup is why there is no separate currency-exchange fee: you buy a CHF-quoted line of an international share, rather than exchanging francs into dollars and buying in New York. The cost of that convenience is the spread, the gap between the buy and the sell price on BX Swiss.
neon says it themselves, quietly. Their FAQ notes that the spread can include a risk premium when liquidity is low, and names the example that matters: US securities in the morning, while the US exchanges are still closed. The practical rule is simple, and no competitor page I have seen states it: buy US names in the afternoon, when New York is open and the spread is at its narrowest. For a monthly ETF plan this barely matters; for larger one-off trades in US shares it is real money.
Opening a neon account is free, takes under ten minutes in the app, and the investing side is switched on from the same login. The welcome bonus lands after sign-up with the reader code.
Is my money safe at neon?
neon is not itself a bank: your account sits at Hypothekarbank Lenzburg, a licensed Swiss bank, and cash balances are covered by esisuisse deposit protection up to CHF 100’000. Your investments are not a bank balance at all: they are securities in a custody account in your name, and their value moves with the market. Deposit insurance is for cash; market risk is yours in every investment account, at neon and everywhere else.
The wider setup, plans, card and the banking side, is a separate topic with its own small print, and I keep all of it in my full neon review. The short version: the everyday account remains my default Swiss account recommendation.
Who shouldn’t use neon invest
Anyone investing large sums in one go. 0.5% on a CHF 50’000 purchase is CHF 250, and 1% on an international share is CHF 500; at a flat-fee broker like Interactive Brokers the same trades cost a few francs. Anyone who wants live markets, limit orders on world exchanges and a research terminal belongs at a broker from my trading comparison. And anyone who does not want to choose investments at all is better served by a managed product: a robo-advisor, or the retirement-first route below.
neon invest vs the alternatives
neon invest vs Yuh
The natural comparison, and the one everyone asks. Yuh charges 0.5% under CHF 10’000 with the rate falling to 0.35% and then 0.25% on bigger orders, so above CHF 10’000 Yuh’s trading gets cheaper than neon’s. Below that, the pricing is near-identical and the differences are structural: neon adds no currency-exchange margin on trades, while Yuh applies its 0.95% FX markup when currency is exchanged, and neon documents securities transfers in and out, while Yuh does not let you transfer securities out at all. Yuh answers back with fractional trading from CHF 10, commission-free ETF savings plans of its own and Swissquote’s banking licence behind it. My honest tiebreak: pick the app whose bank you want for everyday money, because both do the investing basics well.
neon invest vs Interactive Brokers
Not the same tool. Interactive Brokers gives you the world’s exchanges at fees so low they round to zero on small trades, plus every order type ever invented, and in exchange you run a separate account, handle currency conversion yourself and read a denser interface. If you invest more than a few hundred francs per trade in international shares, or your portfolio has outgrown five figures, the move to a real broker pays for itself quickly. If you are saving monthly into an ETF, it solves a problem you do not have.
neon invest vs neon 3a
An order of operations, not a contest. Money for retirement belongs in the neon pillar 3a first: the deposit comes off your taxable income, and the 0.39% to 0.45% fee there has the fund costs of most strategies already inside. neon invest is for money above this year’s 3a maximum, or money you might need before retirement. Same app, same login, different tax treatment, and the tax treatment wins.
The account is free, opening takes under ten minutes with just an ID and a Swiss address, and there is no obligation to invest a single franc. You can open the app, browse all 500-plus assets and read every fee before any money moves.
My rules for neon invest
- Save through the investment plan, not the trading screen. Pick one broad world ETF from the 0% list and automate it monthly. Zero trading fees, no minimum fee, and no willpower required.
- Keep ad-hoc trades above CHF 200. Below that, the CHF 1 minimum fee applies and quietly raises your percentage cost. Above it, you always pay the plain 0.5% or 1%.
- Buy US names in the afternoon. neon’s own FAQ says spreads on US securities can carry a premium in the morning while New York is closed. Wait for the US open and the gap narrows.
- Fill the pillar 3a first. Retirement money gets a tax deduction in the neon 3a; free-savings money does not. The order matters more than the fees.
- Claim the CHF 10. Enter the code investinghero during sign-up. It is a small bonus, but it is one tap.
neon invest FAQ
What is neon invest?
neon invest is the investing feature inside the neon banking app. You can buy and sell over 500 assets, Swiss and international stocks, ETFs and crypto-ETPs, straight from your neon account, with no custody fee and no currency-exchange margin. Trades execute on the BX Swiss exchange in Swiss francs.
What does neon invest cost?
0.5% per trade for all ETFs and Swiss shares, 1.0% for international shares, with a CHF 1 minimum fee on trades outside the investment plan. There is no custody fee and no FX margin. Federal stamp duty of 0.075% on Swiss and 0.15% on foreign securities applies to every trade. Selected ETFs cost 0% inside the investment plan.
Which bank is behind neon?
Hypothekarbank Lenzburg, a licensed Swiss bank in canton Aargau. neon provides the app; the accounts sit at the bank and cash is covered by esisuisse deposit protection up to CHF 100’000.
Is neon invest safe?
The structure is solid: accounts at a licensed Swiss bank, deposit protection on cash, and your investments held as securities in your name. What no provider can remove is market risk, and crypto-ETPs in particular can move violently. The risk in neon invest is what you buy, not where you hold it.
Which ETFs are free in the investment plan?
The 0% list is marked in the app and changes over time. At my last check it included global equity ETFs from Vanguard and Xtrackers, Swisscanto ESG funds, a ZKB gold ETF, a commodities ETF, high-dividend ETFs and the Xtrackers bitcoin and ethereum ETPs. Stamp duty still applies, since it is a federal tax rather than a neon fee.
neon invest or Yuh?
Under CHF 10’000 per trade the fees are nearly identical at 0.5%. Yuh gets cheaper on larger orders and offers fractional trading from CHF 10; neon adds no FX margin and lets you transfer securities out, which Yuh does not. Most people should choose based on which app they want for everyday banking. My full Yuh review has the whole comparison.
Is there a minimum investment?
No. neon sets no minimum or maximum order size, so even CHF 10 a month works. The only thing to know: ad-hoc trades under CHF 200 in ETFs or Swiss shares pay the CHF 1 minimum fee, which the investment plan waives.
Do I pay Swiss stamp duty with neon invest?
Yes, on every purchase and sale: 0.075% for Swiss securities and 0.15% for foreign ones. It is a federal tax collected by every Swiss-domiciled provider, not a neon fee. Foreign brokers do not collect it, which is part of how they price trades lower.
Can I buy bitcoin with neon invest?
You can buy crypto-ETPs, exchange-traded products that track bitcoin, ethereum and other coins, inside the normal app, and two crypto-ETPs sit on the 0% investment plan list. You are holding a security that tracks the coin, not the coin itself. For buying actual coins, my Swiss crypto comparison covers the options.
How does the neon promo code work?
Open your account via my link and enter the code investinghero during sign-up, and neon credits you a CHF 10 welcome bonus. The code field appears in the sign-up flow; it cannot be added afterwards.
Compare & choose
The other comparisons on Investing Hero, each built the same way: every fee read from the provider’s own pricing page.
Where neon invest sits among the brokers is on my Swiss online trading comparison. The account it lives inside has its own page, the full neon review, and if the money is for retirement, start with the pillar 3a comparison instead.
How this review stays accurate. I took every number here from neon’s own pricing page, invest FAQ and investment plan page on 21 September 2026, and I re-verify them whenever this page is updated. If you spot a figure neon has since changed, tell me and I will correct it openly.
Sources. Trading fees, custody and the plan grid from neon’s plans and prices page; fee mechanics, the CHF 1 minimum and stamp duty from the invest fee FAQ and minimum fee FAQ; the asset universe and 0% list from the neon invest page and investment plan page; trading venue and spread behaviour from neon’s own FAQ answers on where investments are traded. All read 21 September 2026. No comparison-site figures were used. Educational content, not financial advice.

